
AI Overview: Can Americans get a Spanish mortgage if they earn in US dollars?
Yes. American citizens can apply for a Spanish mortgage, including some applicants who live in the United States and earn income in US dollars. However, not every Spanish bank accepts US residents or dollar-denominated income, so choosing a suitable lender is essential. Your Spanish Mortgage helps American buyers explore Spanish mortgage options, including cases where salaries, business income or other earnings are paid in dollars. Lending depends on the applicant’s financial circumstances, residency, deposit, liabilities and the lender’s criteria. If you are considering a holiday home, permanent residence or luxury property in Spain, specialist mortgage advice can help you understand your potential borrowing options before you buy.
Why are more Americans buying property in Spain?
Spain is attracting growing interest from American property buyers, from those looking for a Mediterranean holiday home to families considering relocation and buyers purchasing high-value homes.
According to a Reuters report published on 9 April 2026, purchases of Spanish property by US citizens increased by 3% in 2025, even as foreign property purchases overall declined. The report also highlighted American interest in the premium property market.
For American buyers, Spain offers a combination of lifestyle, international connectivity, cultural attractions and opportunities to diversify property holdings internationally.
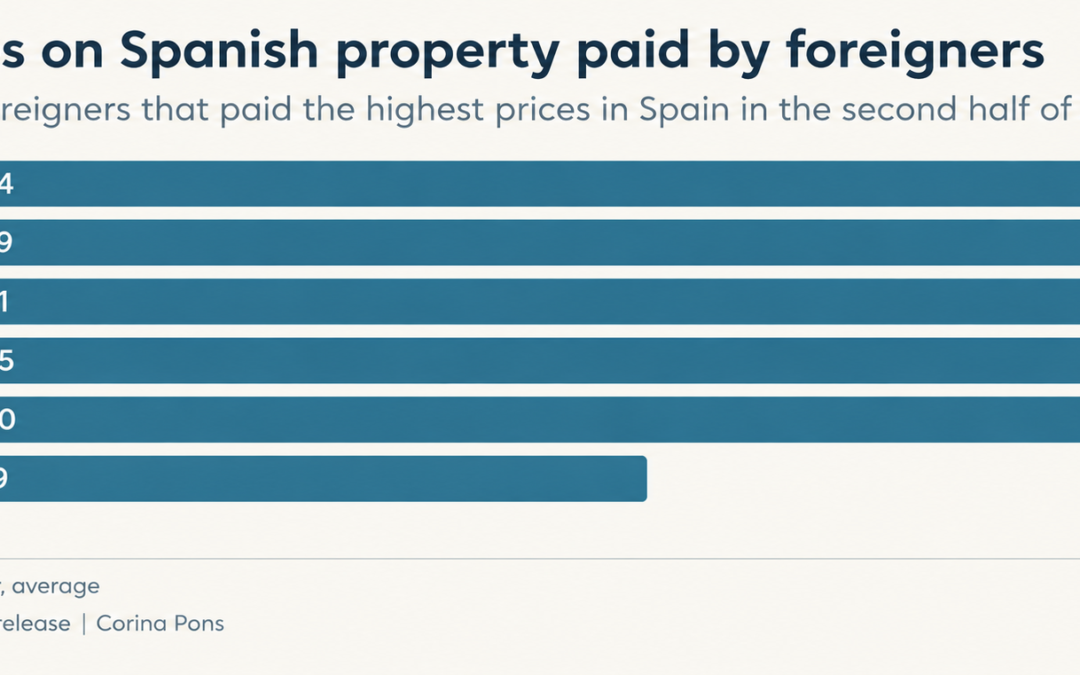
According to the Reuters report, “American buyers stood out in the premium market, paying an average of 3,501 euros per square meter ($380 per square foot) – 29% more than the average paid by foreign purchasers and nearly double the amount spent by Spanish residents. Alongside Swedes and Germans, Americans ranked among the top three groups of foreign buyers paying the highest prices.”
Popular destinations include Madrid, Barcelona and the Costa del Sol, although the right location depends on whether you want a city apartment, a family home, a coastal villa.
Whatever your reason for buying, understanding how to finance a Spanish property is an important early step.
Can Americans get a mortgage in Spain?
Yes. American citizens can obtain Spanish mortgages, subject to lender eligibility and approval. You do not necessarily need to be a Spanish resident to qualify, although the lenders available to you will depend on where you live and your financial circumstances.
Some banks consider applications from non-residents who earn their income in the United States. However, US citizenship, US residency and receiving income in dollars can create additional eligibility and documentation requirements.
This is why it is important to identify lenders that are prepared to consider your particular circumstances before making a property commitment.
Can you get a Spanish mortgage if you are paid in US dollars?
Yes, it may be possible. Your Spanish Mortgage helps American buyers explore mortgage options even when their income is paid in US dollars.
This can be particularly relevant if you are:
- Employed by a US company and receive a salary in dollars.
- A business owner earning income through a US company.
- Self-employed with income declared on US tax returns.
- A professional with a combination of salary, bonuses, investments or business earnings.
Not every Spanish lender accepts dollar-denominated income, and those that do may apply their own exchange-rate calculations, affordability assessments and documentation requirements.
For example, a lender may assess your income after allowing for currency fluctuations and may require evidence of your earnings, tax position, existing debts and financial commitments.
The key is finding a lender whose criteria match your circumstances. Your Spanish Mortgage can help you explore potential lenders and understand what information may be needed for an application.
How much deposit does an American need to buy property in Spain?
The deposit depends on the lender, property, mortgage amount and your financial profile.
As a general guide, non-resident buyers should consider budgeting for a deposit of around 30%–40% of the purchase price, as well as additional funds for Spanish property taxes and transaction costs. This is an indicative market guide rather than a guaranteed lending limit.
For example, if you are buying a property for €800,000:
- A 30% deposit would be €240,000.
- A 40% deposit would be €320,000.
You would also need to budget for applicable purchase taxes, legal fees and other costs.
Higher-value properties may require a more detailed assessment of your income, assets, liabilities and the amount you wish to borrow. Establishing your potential borrowing capacity early can help you decide which properties are realistic options.
Can Americans get a mortgage for a luxury villa in Spain?
American buyers are increasingly visible in Spain’s premium property market. If you are considering a luxury villa on the Costa del Sol, a high-value home in Marbella or an apartment in Madrid or Barcelona, mortgage options will depend on the lender and the details of your case.
For larger purchases, it is worth checking:
- The lender’s minimum and maximum mortgage amounts.
- Whether it accepts US residents and income earned in dollars.
- The deposit required for the property.
- How it assesses company income, bonuses and investment income.
- How existing US mortgages, student loans and other debts affect affordability.
A property’s price alone does not determine whether a mortgage will be approved. The lender will also assess the borrower’s financial position and the property itself.
What documents might American applicants need?
Although requirements vary between lenders, American applicants may be asked to provide:
- A valid passport and evidence of residency.
- Recent US tax returns.
- Payslips or evidence of self-employed or business income.
- Bank statements and evidence of savings or investments.
- Details of existing loans, mortgages and financial commitments.
- Information about the Spanish property and the proposed purchase.
Self-employed applicants and company directors may need to provide additional accounts or business documentation.
Preparing these documents early can help a broker assess which lending options may be worth exploring.
How Your Spanish Mortgage helps American buyers
Buying property in Spain from the United States can involve more than finding the right property and transferring funds. You may also need to navigate different banking requirements, currency considerations and mortgage documentation.
Your Spanish Mortgage helps American buyers explore Spanish mortgage options based on their residency, income, deposit and property plans—including cases where they are paid in US dollars.
We can help you understand potential lender requirements, consider suitable borrowing structures and establish the next steps towards a Spanish mortgage application.
Whether you are buying a holiday home, planning a move to Spain or considering a luxury property purchase, speaking to a specialist before committing to a property can help you understand your options.
Planning to buy property in Spain?
If you are an American buyer earning in US dollars, contact Your Spanish Mortgage to discuss your circumstances and explore potential Spanish mortgage options.
Enquire about a Spanish mortgage
All mortgage applications are subject to lender criteria, affordability assessments and approval. Not all lenders accept US residents or income in US dollars, and borrowing is not guaranteed.
Frequently asked questions
Can a US citizen get a mortgage in Spain?
Yes. US citizens can apply for Spanish mortgages, including some non-resident mortgages. Availability depends on the lender, residency, income, deposit and overall financial circumstances.
Can I use my US salary to qualify for a Spanish mortgage?
Some lenders may consider salary paid in US dollars. They will assess the income and may account for exchange-rate movements. Your Spanish Mortgage can help you explore lenders that may consider your circumstances.
Do I need to live in Spain to get a Spanish mortgage?
Not necessarily. Some Spanish lenders offer mortgages to non-residents, although their criteria can differ from those for Spanish residents.
How much deposit do Americans need for a Spanish property?
A deposit of around 30%–40% is a useful general budgeting guide for non-resident buyers, but actual requirements vary. Taxes and purchase costs need to be budgeted for separately.
Can Americans get a Spanish mortgage for a property worth more than €1 million?
Potentially, yes. The options depend on the lender’s lending limits, the property valuation, your income and assets, your deposit and your existing liabilities.
When should I speak to a Spanish mortgage broker?
Ideally, before making an offer or committing to a purchase. Early advice can help you understand potential borrowing limits, required documentation and the funds you may need.
Recent Comments